ADU (Accessory Dwelling Unit) Insurance
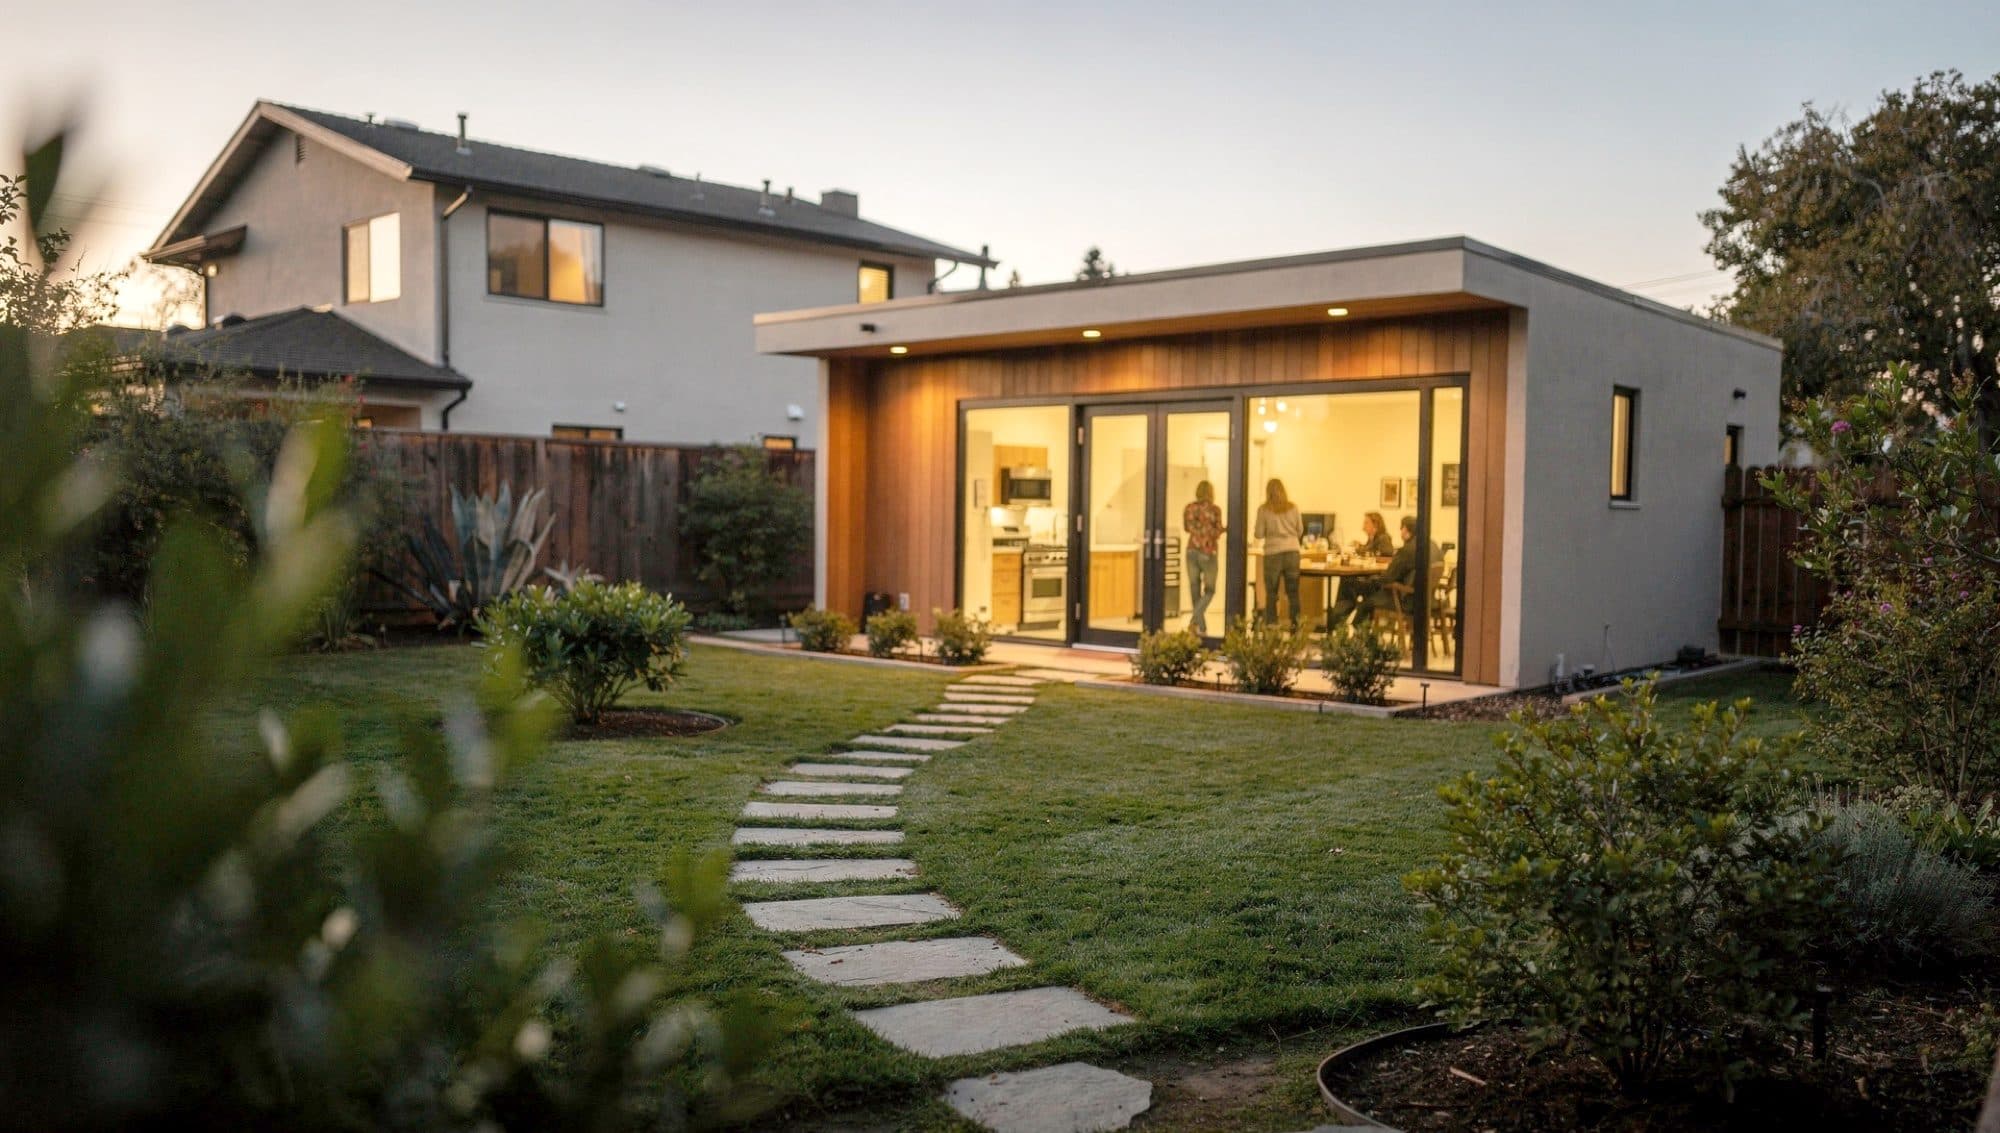
Added a granny flat, in-law unit, or backyard rental? Your existing homeowners policy may not automatically extend to it. We help Bay Area homeowners make sure their ADU — whether owner-occupied or rented out — is properly covered for structure, liability, and lost rental income.
What it covers
- The ADU structure itself, as a separate insured building
- Liability protection for injuries that happen in or around the unit
- Lost rental income if the unit becomes uninhabitable after a covered loss
- Contents you own inside the unit, including appliances and furnishings
Who needs it
Homeowners who have built, converted, or are planning an accessory dwelling unit — a garage conversion, a basement or in-law unit, or a detached backyard cottage.
It matters most once the unit is occupied by someone other than your household, because that changes how a carrier treats the property.
Common gaps we see
Homeowners commonly assume the ADU is automatically covered as an "other structure" on their existing policy. That coverage is often limited to a percentage of the dwelling limit and may exclude the unit entirely once it is rented. Tell your carrier the unit exists — an undisclosed rental unit is a common reason claims get denied.
How SureNest helps
As an independent broker, we compare multiple carriers to match your situation with the right policy — not a one-size-fits-all plan pushed by a single insurer.